
Commercial property, bought on your side.
Commercial can add income and balance to a portfolio. It only works if the tenant, the lease and the price stack up. We check all three before you sign anything, and we'll tell you if it doesn't.
No pressure. Just clarity.
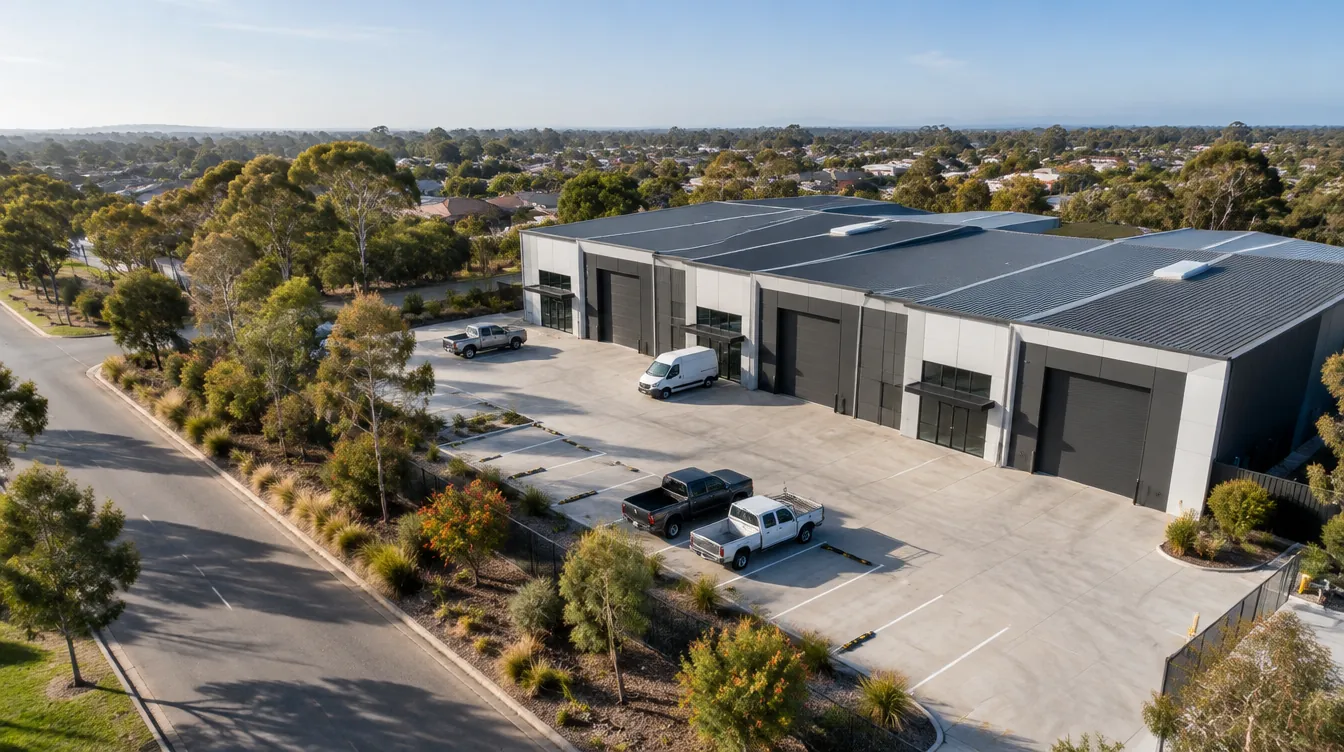
The wrong property is the risk.
Not commercial. Not residential. The wrong one, bought for the wrong reasons, at the wrong price. That's what we protect you from.A different game, with different rules.
Residential is our bread and butter, and for most clients it's the foundation. It's driven by land, location and long-term growth. Commercial is driven by the tenant, the lease and the income.
For the right client, at the right stage, commercial sits alongside a strong residential portfolio and adds income and balance. We help you work out whether it's the right next move. If it is, we find it, check it properly and negotiate like it's our own money.
Residential and commercial do different jobs.
Neither is better. They work differently. Here's how they typically compare, so you can see what changes.
Residential
Commercial
General comparison only. Every deal is different, and we'll show you the real numbers, with sources, for your situation.
Is commercial right for you, right now?
It isn't for everyone, and it isn't usually the first move. Pick the one that sounds most like you.
“Another purchase isn't a strategy.”Manny · Founder
Commercial usually works best as a later move, once residential has done the heavy lifting on growth. Before we buy anything, we load your real portfolio into our modelling tool and test when commercial makes sense, and what it does to your cashflow, borrowing and wealth. Every single year.
Everyday assets. Essential tenants.
Businesses people rely on, in locations that make sense. Not trophy assets, not speculation.
Industrial and warehouse
Small to mid-size units and sheds with trades and logistics tenants.
Neighbourhood retail
Strip shops and convenience retail serving the local community every day.
Medical and allied health
GP clinics, dental, physio and specialists, often on long, sticky leases.
Childcare
Purpose-built centres with experienced operators and long lease terms.
Suburban office
Smaller suites outside the CBD with professional services tenants.
Showroom and large format
Bulky goods and trade showrooms on busy, visible roads.
The deal behind the building.
In commercial, the brochure is the least important document. Before we tell you we'd buy it, we pull apart six things. If any of them fails, we'll say so.
Who pays the rent
How long they've traded, how strong the business is, and whether they actually need this location.
What it really says
Term remaining, rent reviews, options, outgoings recovery, make-good, and anything that shifts risk back to you.
What the income is worth
Yield against real comparable sales, so you pay for the income, not the marketing.
If the tenant left tomorrow
How fast, and at what rent, could it be re-let? We plan the exit on day one.
Site and zoning
Exposure, access, parking, nearby supply and council plans that could help or hurt the site.
Condition and compliance
Fire and safety compliance, and the capital works a vendor won't mention.
We'd rather lose a deal than see you make the wrong one.
- A tenant with no trading history and a personal guarantee that doesn't cover the risk
- A lease that ends before your loan term, with no options left
- Rent sitting well above what the market would pay a new tenant
- A yield that only works because of incentives the next buyer won't get
- Capital works the vendor hasn't disclosed or priced in
- A structure that doesn't suit how you're buying it, especially in super
What you'll hear elsewhere, and what we say.
Not the loudest voice in property. The clearest. Calm in a downturn, no hype in a boom.
Income first, then growth.
Commercial is valued mostly on the rent it earns. A longer lease with a stronger tenant usually means a more valuable property.
It's a trade-off, not a free lunch. Move the sliders to get a feel for it, then we'll show you real options, with the numbers behind them.
The same five steps. Built for commercial.
The process our residential clients trust, with the extra layers commercial brings. You're kept in the loop, without managing any of it.
Strategy
Where you are, what you want commercial to do, and whether it's the right move yet. Modelled before we search.
Search and Access
On-market, off-market and pre-market, through our agent network, filtered hard against your brief.
Assessment
Tenant, lease, price, re-leasing risk, site and building. Your adviser and accountant set the structure, your broker handles the loan. We never recommend lenders.
Negotiation
Price and lease terms, negotiated like it's our own money.
Protection
Reports, conditions and settlement, then ongoing reviews of the asset inside your portfolio.
Same team. Same standards.
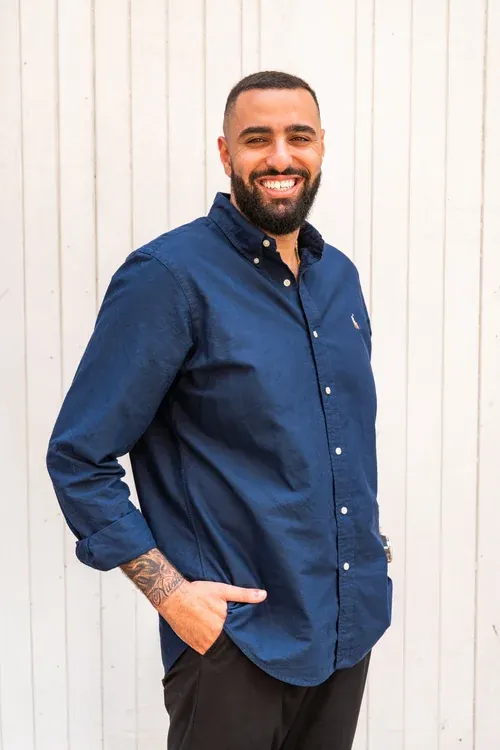
Emmanuel Michael
Manny asks “should you?” and makes sure commercial fits the bigger plan, and the life behind it, before anything else. Most at home fixing portfolios built one purchase at a time.
Here are your options. Here's why this one, not that one.
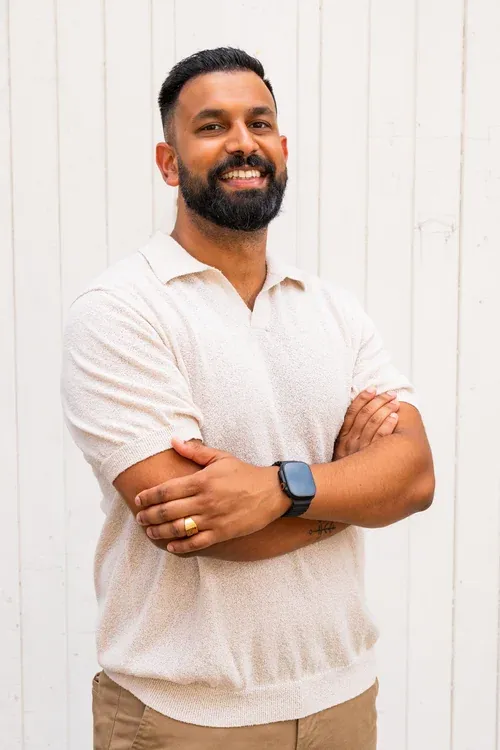
Kej Kulane
Kej asks “would we?” and leads the data, the lease review and the negotiation. Evidence first, explained plainly.
Here's what the headline isn't telling you.
Commercial FAQs.
Something we haven't covered? Ask us directly. You'll get a straight answer.
Book a consultationWhat budget do I need for commercial?
Our commercial purchases start from $1 million. Lenders usually want a 30 to 40% deposit, so your available cash or equity matters as much as the price. We'll work it out with you on the first call.
Should commercial be my next purchase?
Often not yet. For most clients, residential does the heavy lifting on growth first, and commercial comes later for income. We model both paths on your real numbers before we recommend either.
Can I buy commercial property in my SMSF?
Some people can, through an SMSF. It's complex, and whether it suits you is personal financial advice, so that decision sits with a licensed financial adviser. Once you have advice, we handle the property side.
Do the new rules affect commercial property?
The 2026 Budget changes to negative gearing and capital gains tax, as announced, have a lot of people asking. How they apply depends on the property and how you own it, so your accountant should confirm your position. We'll walk you through what was announced, in plain English.
Will you tell me if I shouldn't buy?
Yes. We're buyer-only, and we'd rather lose a deal than see you make the wrong one. Sometimes the best advice is to wait.
Is commercial riskier than residential?
The risks are different. Income is often higher and leases longer, but a vacancy can last longer and lending is tighter. That's why our diligence focuses on the tenant, the lease and re-leasing risk.
How are you paid?
A transparent fee agreed upfront. We don't take commissions from sellers, agents or developers, so the only person we work for is you.
Can I buy my own business premises?
Yes. We'll help you weigh up the price and the lease terms between your business and the buying entity, with your accountant advising on the structure.
Where do you buy?
Australia-wide. InvestorMate is licensed in NSW and buys commercial property right across the country, wherever the deal and your brief line up.
Own well. At your own pace.
Small steps first. Read how we think, watch how we break down a deal, then talk to us when you're ready.
Articles, coming soon
Plain-English breakdowns of the market, the rules and the calls we'd make.
See what's coming 02 · WatchYouTube breakdowns
Real markets, real numbers, and the calls we'd make. Evidence first, then a point of view.
Watch now 03 · ModelPortfolio modelling
See what commercial, or one more resi purchase, does to your next 20 years.
See how it worksLet's talk commercial.
A straight conversation about whether commercial fits your plan. If it doesn't, we'll tell you.
No pressure. Just clarity.
General information only, not personal financial or tax advice. It doesn't take into account your objectives, financial situation or needs. Speak with a licensed financial adviser, your accountant and your broker before making investment decisions, particularly before buying through an SMSF. Yields, ranges and projections shown are general and illustrative, not a promise of future returns. Licensed corporation: EGM Property Group Pty Ltd trading as InvestorMate, NSW Fair Trading corporation licence 10136675, ACN 664 799 035.